Paying for Car Damage
Who pays for the damage depends on who caused the accident and which coverages are on your policy.
It depends on fault and your coverage, not just the damage itself
If the accident was someone else's fault, their liability coverage is supposed to pay for your damage. If it was your fault, your own collision coverage pays, if you carry it. If you don't carry collision, you pay out of pocket.
What changes this is whether you have collision and comprehensive on your policy, and whether the other driver actually has insurance that will pay. A driver your age who has paid off their car sometimes drops collision coverage to save money, which means an at-fault accident becomes a bill they pay themselves.

Whether you carry collision coverage changes everything
Liability coverage, which almost every state requires, only pays for damage you cause to someone else. It does nothing for your own car. If you want your insurer to pay for damage to your own vehicle, whether you caused the accident or not, you need collision coverage, and for things like hail or a tree branch, comprehensive coverage.
If you're not sure which of these you have, your policy declarations page will list them by name. It's worth checking before anything happens, not after.
Some drivers reach a point where the car is worth less than a year or two of collision premiums combined. At that point, paying for repairs yourself if something happens can cost less over time than carrying the coverage. That's a decision worth making deliberately, not by accident.
If you drop collision, understand what that means. A deer, a pothole, an at-fault fender bender, any of it becomes your bill.
Filing a claim isn't free even when it isn't your fault
If the other driver is clearly at fault and insured, you can usually go through their insurer directly instead of your own. This avoids your deductible and keeps the claim off your own record.
If fault is disputed, or the other driver is uninsured or underinsured, you may need to file through your own policy and let your insurer pursue the other side. This is faster but it uses your deductible upfront, even though you may get it back later.
Even a claim that isn't your fault can affect your rate at renewal, depending on your insurer's rules. Ask your agent directly how they handle not-at-fault claims before you assume it won't matter.
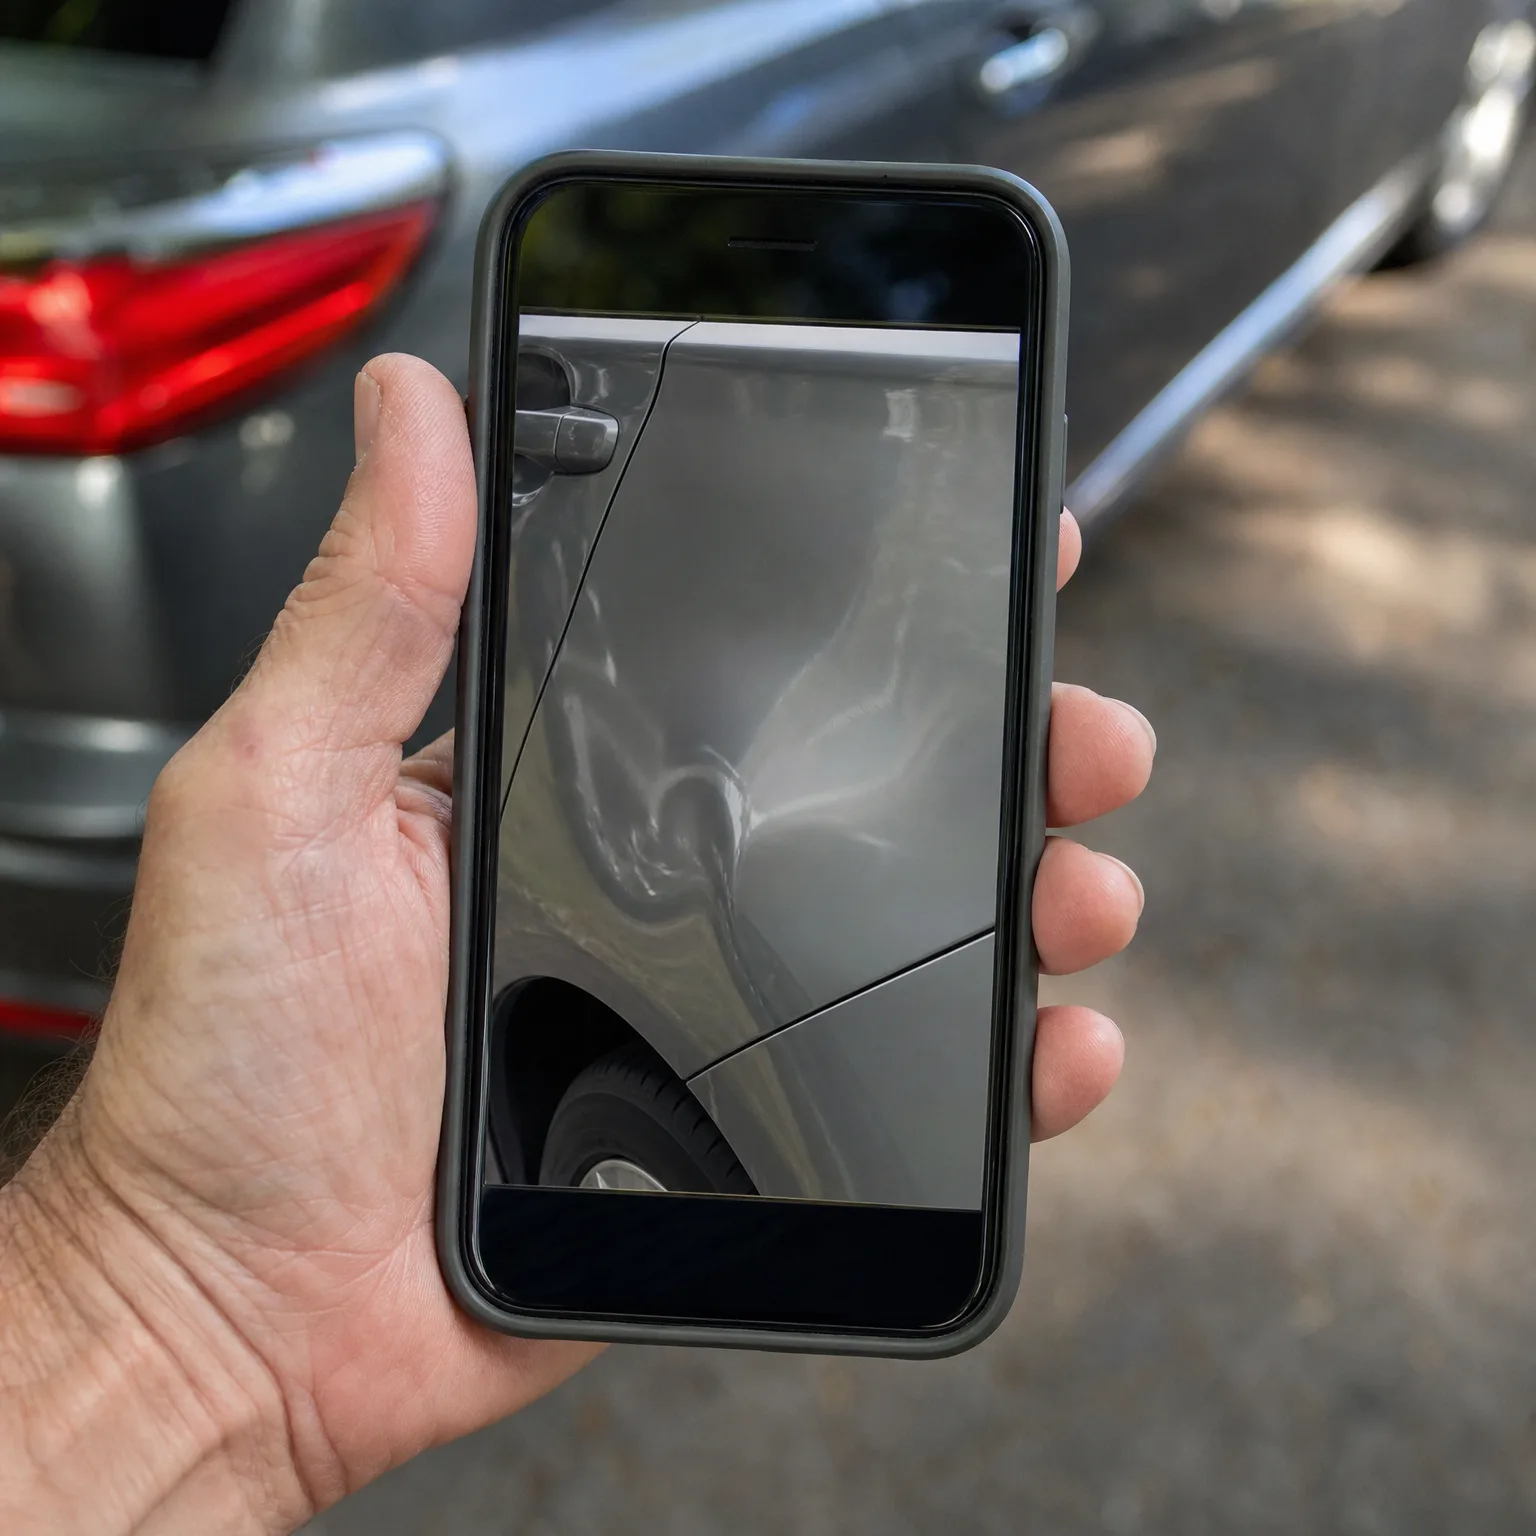
Getting repair estimates from more than one shop is reasonable and most insurers expect it. You don't have to accept the first number you're given.
Questions people ask about this
Do I have to use my insurance company's recommended repair shop?
No, you generally have the right to choose your own repair shop. Insurers often suggest shops they work with regularly because it can speed up the process, but the choice is yours. Ask your insurer whether using an outside shop affects how the estimate or payment is handled.
What happens if the other driver has no insurance?
This is what uninsured motorist coverage is for, if you carry it. Without it, you'd need to pursue the other driver directly for payment, which can be difficult. Check your policy to see if you have this coverage, since it isn't required everywhere.
Will my rate go up if I file a claim that wasn't my fault?
It depends on your insurer and sometimes on your state's rules about surcharging. Some insurers have accident forgiveness that prevents this for a first incident. Ask your agent directly how not-at-fault claims are treated before deciding whether to file.
Can I just pay for the damage myself instead of filing a claim?
Yes, nothing requires you to file a claim for damage to your own car. Some drivers do this when the repair cost is close to their deductible, since filing wouldn't save much money but could affect their rate. Compare the repair estimate to your deductible before deciding.
Does it matter who was driving the car when the damage happened?
Usually the policy follows the car, not the driver, so your coverage typically applies regardless of who was behind the wheel, as long as they had permission to drive it. This can vary by state and by insurer, so check your policy's language on permissive use.
See what collision and comprehensive coverage would cost to add or keep on your policy.
Pull out your policy declarations page this week and confirm whether you currently have collision and comprehensive coverage, not just liability. If you're not sure what a term means, call your agent and ask them to walk through it line by line. If you're considering dropping collision coverage, ask your agent for your car's estimated value first, so you're comparing it against the coverage cost rather than guessing. And if you're ever in an accident, get a repair estimate before agreeing to anything, whether you're filing through your insurer or the other driver's.